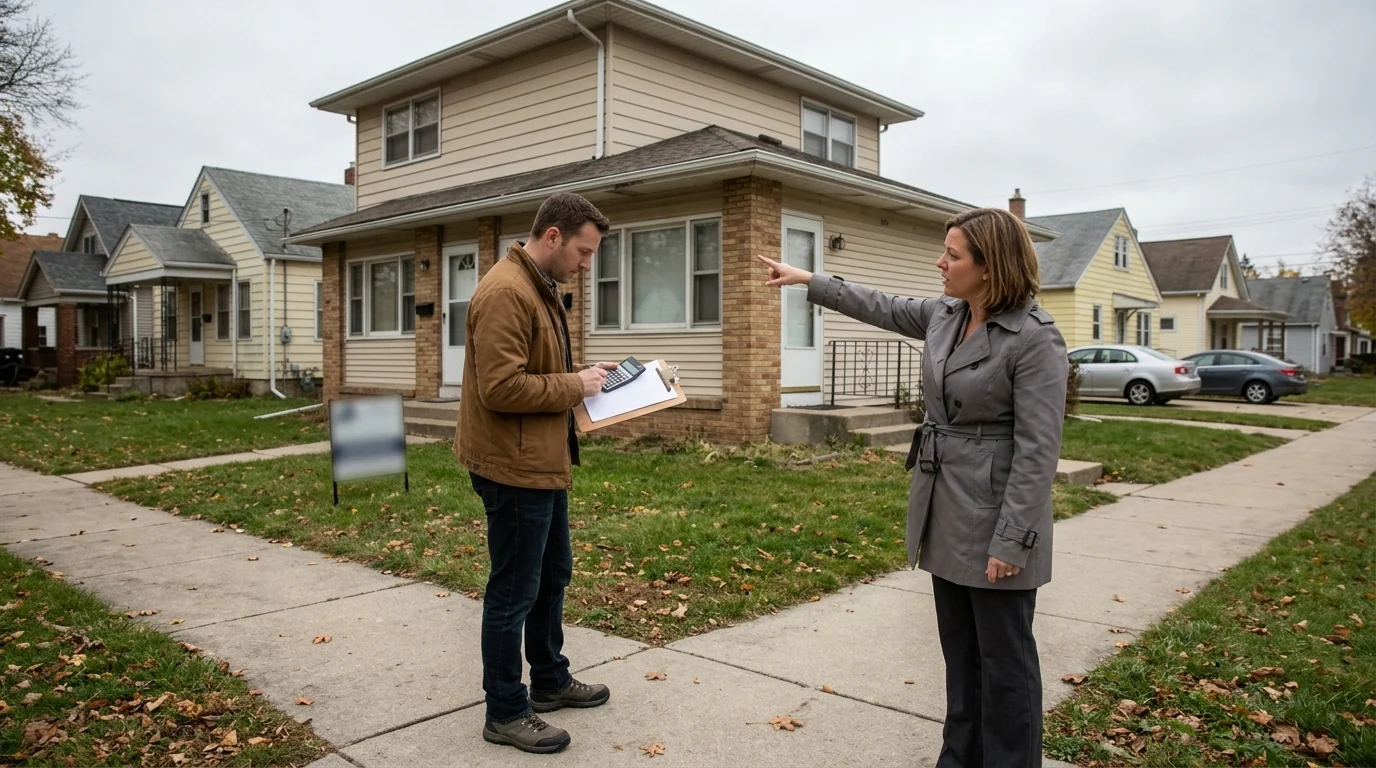
A recession can squeeze income, tighten credit, and expose weak financial habits fast. The biggest mistakes usually come from reacting emotionally—either freezing completely or taking desperate risks. Avoid these common missteps to protect cash flow now and keep options open when conditions improve.
Trying to “ride it out” without knowing your monthly burn rate is risky. Track essential expenses, minimum debt payments, and reliable income sources. Build a realistic buffer and make cuts early, before you’re forced into expensive last-minute decisions.
Using credit cards, buy-now-pay-later plans, or high-rate personal loans to cover non-essentials can turn a temporary downturn into a long-term problem. If you must borrow, prioritize the lowest rate available and a payoff plan that fits a conservative budget.
Dumping investments or property solely because headlines feel scary often locks in losses. If you need liquidity, consider selling strategically (and slowly) rather than liquidating everything at once. Decisions should be based on your time horizon, reserves, and required monthly obligations—not fear.
A recession is not the time to stretch to the maximum loan approval or assume future raises will cover higher payments. Keep extra room for repairs, vacancies, medical costs, or rate changes. This is especially important with real estate, where carrying costs can surprise even experienced buyers.
Discounts can be real, but so can hidden issues: deferred maintenance, unstable tenants, or neighborhood demand shifts. Treat every “deal” like a full-price purchase—inspect, verify numbers, and plan for worst-case scenarios. For a practical property-focused checklist, see this guide to buying property in a downturn.
Waiting to upskill, diversify income, or strengthen client pipelines can cost more later. Focus on reliable revenue, transferable skills, and reducing single points of failure in your finances.
Prioritize an emergency fund, reduce high-interest debt, and map out essential expenses. Keep a conservative budget and avoid taking on new fixed monthly commitments.

Leave a comment